Bank deposits, demat investments in single account statement soon
Come January 1, customers will be able to view their savings and investments across asset classes in a single monthly statement, with the Reserve Bank of India (RBI) on Wednesday allowing depositories regulated by the Securities and Exchange Board of India (Sebi) to include bank deposit information in their Consolidated Account Statement (CAS) through NBFC-Account Aggregators (AAs).
“This will enable demat account holders to view information relating to their demat account holdings and bank deposit accounts at one place in the CAS,” the RBI said.
Currently, mutual fund (MF) and stock market investors receive a CAS every month consolidating transaction details across MF schemes and securities held in demat form under a single Permanent Account Number (PAN). Retirement savings through the National Pension System (NPS), regulated by the Pension Fund Regulatory and Development Authority (PFRDA), have also been integrated into the CAS. Bank deposits, however, are not covered, leaving a key component of financial savings outside the statement.
The move will bring bank deposits into the fold, giving individuals a consolidated view of their financial assets.
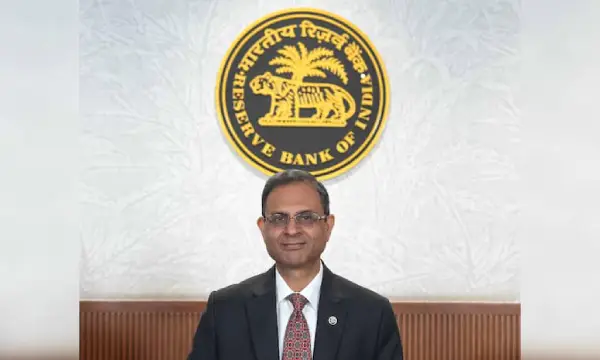
“We are now trying to facilitate information relating to bank deposits across all banks that are already onboarded, while the rest will be brought on board over a period of time, so that the information can be made available to customers through CAS,” said RBI Governor Sanjay Malhotra.
This will empower consumers, Malhotra said. “We see a lot of cases of bank deposits getting lost, especially when people die, so this will help address that because you have one consolidated view.”
The CAS is sent by depositories to investors’ registered email addresses and provides details such as the current value of investments, returns, and expenses and commissions paid on MF investments. Information on e-insurance accounts is also available if the details are held in the National Insurance Repository.
There are two Sebi-regulated depositories in the country — National Securities Depository Limited (NSDL) and Central Depository Services (India) Limited (CDSL). They hold investors’ securities, including shares and bonds, in electronic or dematerialised form.
According to Sahamati Chief Executive Officer B G Mahesh, bringing bank deposits into the CAS could enable a more connected view of an individual’s financial life. “Together, these steps can accelerate the shift from AA as a data-sharing mechanism to a foundational layer of India’s digital financial infrastructure, enabling financial services to be accessed and delivered more seamlessly across institutions,” Mahesh said.
The move is also expected to improve the ability of financial institutions to profile customers and customise products and services. “The measure will entail better financial profiling of customers, hyper-customisation of services and integration of services across financial services,” SBI Research said in a note.
Harsh Roongta, founder of Fee Only Investment Advisors LLP, said the consolidated statement would help people plan their finances better and also the families trace assets left behind by a deceased investor, including those that might otherwise remain unclaimed. “Hopefully, insurance policies and EPF balances will also be included in due course,” he said.
Interoperability among account aggregators
Separately, the RBI will introduce interoperability among NBFC-account aggregators (AAs), allowing customers to access and share financial data across different AA providers through a single aggregator of their choice.
Both measures are expected to be implemented by December 31.
“This is a step towards integrating information that could previously be accessed through a number of account aggregators. The information was disaggregated, but by integrating it, it is now possible for individuals, as well as other entities such as insurers, stock brokers, asset managers and investment advisors, to access the data with the consent of the individual concerned and provide appropriate advice,” Mahesh said.
Interoperability is a natural next step in the evolution of the AA framework as digital financial infrastructure and as a key layer of India’s Digital Public Infrastructure, Mahesh said. The ecosystem has crossed 500 million fulfilled consents and enabled the delivery of more than 74 million financial services across lending, capital markets and insurance in FY26.
“This demonstrates that consent-based data sharing is already operating at a meaningful scale,” he added.
AAs are non-banking financial companies licensed by the RBI to act as a bridge between Financial Information Providers (FIPs) and Financial Information Users (FIUs). They facilitate the secure transfer of customers’ financial information, with their consent, from institutions that hold the data to those that use it to provide financial services.
FIPs include banks and NBFCs that hold customers’ financial information, while FIUs use the data to provide services such as loans, insurance and wealth management.
As many as 17 RBI-licensed AAs, including CAMSFinServ, CRIF Connect, NESL Asset Data, Protean, and PB Financial, are active in India.
As of August, 338.04 million accounts were linked through the AA framework, up 24 per cent from 272.46 million in February. In August alone, 11.72 million accounts were linked and 27.94 million new consents were fulfilled.
The cumulative number of consents fulfilled stood at 566.26 million as of August. AAs delivered 352.48 million datasets on linked accounts during the month, the highest monthly level between February and August, compared with 265.67 million datasets delivered in February, underscoring the growing use of the framework for sharing financial information.
Other Latest News
Air India will offer travel SIM cards to passengers for their overseas trips.
EasyRoam, an Air India-branded travel SIM card that offers international roaming services, has been developed in partnership with Tata Communications.
The ancillary product will be available for purchase as a physical SIM card as well as eSIM on a dedicated Air India-branded webpage.
The BJP on Thursday alleged that the Congress is trying to create "Nepal- and Bangladesh-like anarchy" in the country through its street protests, as Rahul Gandhi is "desperate" to come to power.
Showing some video footage of INDIA bloc' Wednesday protest, BJP spokesperson Pradeep Bhandari said the way Rahul.
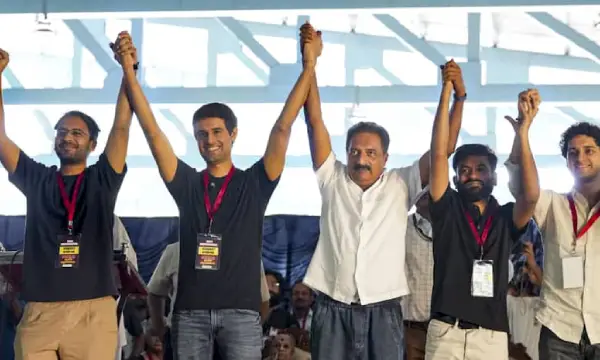
CJP founder Abhijeet Dipke, YouTuber Dhruv Rathee and actor-activist Prakash Raj led a protest here on Thursday against CEC Gyanesh Kumar, demanding his immediate resignation over alleged irregularities in the SIR of electoral rolls.
Protesters from various walks of life, including women and students, gathered in large numbers at Freedom Park and the mood dramatically turned electric.
India’s communications ministry on Thursday said it followed a “fair and non-discriminatory” authorisation framework for all telecommunication services, including satellite communication services, and that preferential clearance of any single operator would be inconsistent with that regulatory environment.
In a statement, the ministry said security assessment was part of the process and was currently under way for all three licensees. Once completed, the companies would move to the next stage of seeking spectrum assignment.
Dismissing Elon Musk's allegations that his satcom company Starlink is being blocked in India, Bharti Airtel chairman Sunil Bharti Mittal said that even his satcom venture, Eutelsat OneWeb, is awaiting approvals to start operations.
On Wednesday, Musk alleged that "certain oligarchs" have blocked Starlink in India to maintain their monopoly.