NSE's ₹4.45 trillion valuation nearly double that of BSE, MCX, IEX combined
Today's market debut has propelled National Stock Exchange (NSE) among India's most valuable companies and firmly established it as the country's biggest listed exchange by market capitalisation (m-cap). Valued at ₹4.45 trillion on listing, NSE is now worth twice the combined m-caps of BSE, Multi Commodity Exchange (MCX) and India Energy Exchange (IEX), India's other listed exchange businesses.
Together, the market caps of these companies was worth ₹2.28 trillion. BSE's market cap stood at ₹1.31 trillion, MCX's at ₹86,875 crore and IEX's at ₹9,973 crore as of 10 AM.
NSE shares listed at ₹1800 today, up 0.84 per cent from the IPO price of ₹1,785.
The valuation reflects NSE’s dominant market position, strong profitability, and network-driven business model, said Vinit Bolinjkar, head of research at Ventura. Compared with peers such as BSE, MCX, and IEX, NSE operates a broader multi-asset exchange ecosystem covering equities, derivatives, currencies, debt, clearing, indices, data services, and technology solutions, noted Bolinjkar, thus giving it an edge.
The two things to watch on day one, according to Harshal Dasani, business head at INVasset, are whether the thinly subscribed retail float holds, and whether institutions allotted a fraction of their bids buy the balance in the secondary market, he said.
NSE is India’s largest exchange by trading activity, with FY26 market shares of 92.99 per cent in cash-market turnover, 99.79 per cent in equity futures, and 74.71 per cent in equity options premium turnover.
How should investors approach exchange business?
Exchanges are toll roads on activity, which, according to Dasani, makes them the best business model in financial services and the most cyclical one at the same time.
Revenue is driven by two things: trading volumes and fees. Volumes depend on the market cycle, while fees are largely set by regulators. Dasani suggests looking at the exchange business through three lenses.
First, watch regulatory risk. Changes to derivatives lot sizes or trading charges can move stocks more than quarterly earnings. IEX is a case in point: Its 85 per cent market share is being repriced as regulators move towards market coupling, pushing its valuation down to 21 times earnings versus nearly 50 times for peers, Dasani said.
Second, back the share-taker, not the incumbent. At this scale, growth often comes from taking market share, he noted, adding that BSE's profit rose 62 per cent in the June quarter, even as NSE's FY26 profit fell 15 per cent.
Third, treat valuations as a bet on volumes. BSE and MCX, trading at 48–53 times earnings, need sustained growth in activity to justify those multiples. NSE's listing at around 43 times FY26 earnings could also set a valuation benchmark for the sector, he said.
"The framework suits patient capital that sizes positions for a cycle rather than a quarter and treats each regulatory consultation paper as the real earnings event."
Other Latest News
The Insurance Regulatory and Development Authority of India (Irdai) on Wednesday proposed a phased reduction in the expenses of management (EoM) limits for insurers, with life insurers required to bring company-level EoM down to 15 per cent of gross direct premium income (GDPI) within two years and 12.5 per cent within five years.
Traders and business associations across India have announced a “No UPI Day” on October 2 to protest the 0.4 per cent merchant discount rate (MDR) on Unified Payments Interface (UPI) transactions above ₹2,000 from October 15.
They plan to cover UPI scanners, QR codes, sound boxes and other related devices with black cloth as a mark of protest on October 2, which is also observed as Gandhi Jayanti across the country.
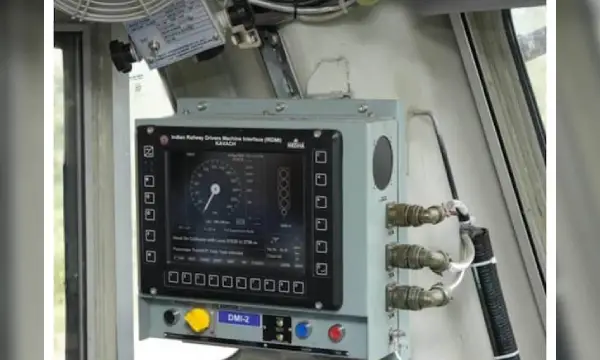
Indian Railways has commissioned Kavach Version 4.0 for the first time on the South Central Railway (SCR), marking the next phase in its rollout of the indigenous Automatic Train Protection (ATP) system.
The upgraded automatic train protection system is now operational across 108 route kilometres on the Malkajgiri–Kamareddi section of the Hyderabad Division.
The Election Commission of India (ECI) on Wednesday said its internal notes, observations and differing views were part of its standard decision-making process and that its final decisions over the past year had been unanimous, after an investigation by The Indian Express claimed that two Election Commissioners had repeatedly objected to key steps concerning electoral rolls.
All banks, including Regional Rural Banks, will remain open on Sunday for the convenience of customers in view of a strike called by the United Forum of Bank Unions (UFBU), the finance ministry said in a statement on Wednesday.
The UFBU, which claims to represent 90 per cent of the banking workforce, is set to go on a three-day strike beginning September 28, primarily seeking a 5-day banking week, among other demands.